Market overview of the Zirconium Tube Rod Market
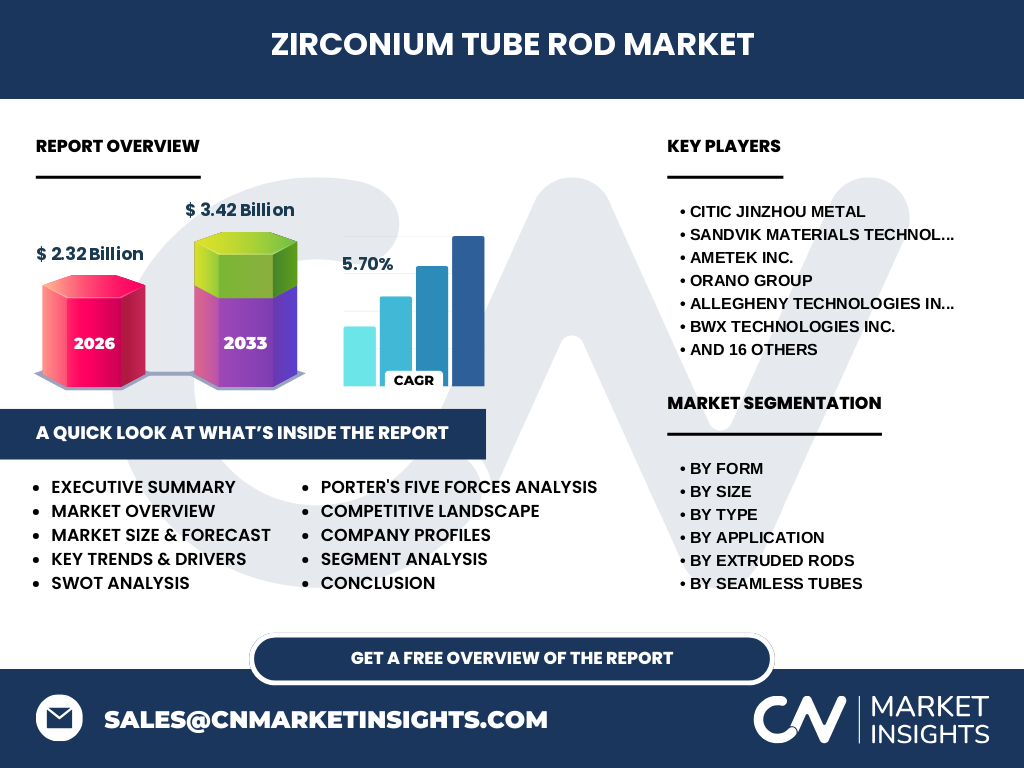
Our analysis indicates that the Zirconium Tube Rod Market represents a critical sector within advanced metallurgy, valued at 2.32 Billion in 2026. This market encompasses specialized production of solid rods, hollow tubes, and extruded forms utilized in extreme environments requiring exceptional corrosion resistance and low thermal neutron absorption cross-sections.
Structural Growth Drivers and Restraints in the Zirconium Tube Rod Market
The market is propelled by expanding nuclear energy programs and rigorous chemical processing demands, though tempered by the high cost of sponge zirconium extraction. Regulatory oversight by bodies like the Nuclear Regulatory Commission (NRC) strictly dictates purity standards, limiting supply chain flexibility for emerging manufacturers.
Emerging trends and growth patterns in Zirconium Tube Rod Market
Technological advancements in precision extrusion are transforming production methodologies across mills in Baoji and beyond. Industry participants are increasingly shifting toward advanced alloy variants like Zircaloy 4 and Zirconium Niobium to meet heightened operational thresholds in aerospace and medical device applications.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain disruptions temporarily stalled raw material shipments through major maritime hubs, creating a backlog in reactor-grade tube procurement. However, aggressive post-pandemic fiscal stimuli directed toward green energy infrastructure catalyzed a robust recovery across core end-user industries.
Competitive benchmarking and strategic dynamics
The competitive landscape features a blend of state-backed entities and specialized private metallurgists. Firms like CITIC Jinzhou Metal and Sandvik Materials Technology dominate through integrated supply chains, whereas specialized players focus on precision machining and custom-sized alloy delivery.
Executive summary of key findings for the Zirconium Tube Rod Market industry trends
The Zirconium Tube Rod Market industry trends point toward a sustained expansion trajectory, supported by a projected market size of 3.42 Billion by 2033. Achieving a 5.70% CAGR, the sector rewards investments in high-purity, corrosion-resistant manufacturing capabilities.
Market forecast from 2027 to 2033
Based on our research, the market will scale from its 2026 baseline to 3.42 Billion by 2033, registering a steady 5.70% CAGR. Increased deployment of small modular reactors (SMRs) serves as the primary catalyst accelerating demand for reactor-grade seamless tubes during this forecast window.
Segmentation analysis across forms, sizes, and types
Segmentation spans multiple categories, including Form (Solid Rods, Hollow Tubes, Welded and Seamless Tubes), Size (Small, Medium, Large Diameter, and Custom Sizes), and Type (Pure Zirconium and Zirconium Alloy variants). Each segment addresses specific industrial tolerances, from high-pressure chemical loops to sensitive medical implants.
Regional market analysis and geographic distribution
Geographic performance is heavily concentrated in regions with robust nuclear power generation and advanced aerospace manufacturing infrastructure. Asia-Pacific leads volume consumption, driven by dense manufacturing clusters in China, while North America and Europe maintain dominance in high-purity aerospace specifications.
In-depth regional review of high-growth territories
Our analysis highlights Baoji City as a global epicenter for non-ferrous metal processing, housing key innovators like Baoji City Changsheng Titanium and Baoji ChuangXin Metal Materials. Meanwhile, North American demand remains anchored by strict military and aerospace procurement standards managed by entities like Allegheny Technologies.
Company profiles and strategic positioning
Leading industry participants leverage distinct operational advantages. Orano Group and BWX Technologies focus on nuclear-grade fuel assembly components, whereas firms like Tricor Metals and Heeger Materials specialize in corrosion-resistant linings and custom alloy rods for aggressive chemical processing environments.
Porter's Five Forces analysis of competitive intensity
The threat of new entrants is moderate-to-low due to prohibitive capital expenditure requirements and strict nuclear certification barriers. Supplier power remains balanced, constrained by the specialized nature of sponge zirconium mining, while buyer power is neutralized by the critical necessity of failure-resistant materials.
SWOT analysis of the Zirconium Tube Rod Market market size and dynamics
Strengths include unmatched corrosion resistance and neutron transparency; weaknesses involve high material costs. Opportunities lie in emerging green hydrogen production, while threats stem from potential substitution by advanced titanium alloys or ceramic composites in less extreme thermal environments.
Value chain analysis from raw materials to end-users
The value chain initiates with zircon sand extraction and chemical separation of zirconium from hafnium, progressing through sponge reduction, vacuum arc melting, and precision extrusion. Finished tubes and rods flow directly into tier-1 manufacturers servicing the energy, aerospace, and medical sectors.
Investment insights and high-potential growth areas
Strategic investments should target precision extruded rods and reactor-grade seamless tubes, which command superior profit margins. Companies prioritizing R&D in zirconium-niobium alloys will capture outsized market share as stringent environmental regulations force industrial operators to upgrade containment infrastructure.
Conclusion and key takeaways for stakeholders
The Zirconium Tube Rod Market offers compelling growth backed by a 5.70% CAGR through 2033. Stakeholders must navigate high input costs by forging direct supply partnerships with primary producers and investing heavily in advanced alloy customization capabilities.
Research methodology and baseline estimation techniques
Baseline estimates are triangulated by cross-referencing trade registry data from customs authorities, primary stakeholder interviews with c-suite executives across CITIC Jinzhou Metal and Sandvik Materials Technology, and secondary macroeconomic indicators tracking global energy capital expenditures.
Scope of the report and coverage parameters
This report covers global production, consumption, trade flows, and technological evaluations of zirconium tubes and rods across 2026 to 2033. Limitations include restricted transparency on state-owned enterprise production quotas in certain localized Asian manufacturing jurisdictions.
Recent developments, partnerships, and strategic moves
Recent industry momentum features strategic capacity expansions among Baoji-based producers and joint ventures focused on high-purity reactor components. Key players are actively optimizing their supply chains to mitigate raw material price volatility while scaling production for next-generation nuclear facilities.